
How the Live-In-Then-Rent Strategy Can Help You Start Investing in Real Estate
Real Estate CoachingBy Cynthia Meyer, CFA®, CFP®, ChFC®
What you will get from this article:
Many real estate investors think of buying their first home and buying a rental property as two separate goals; you buy your home to live in and hope to build wealth with another property that can be rented out.
And that’s certainly one way to do it, but for some first-time buyers, the first home can also become the first step toward building a real estate portfolio.
With the live-in-then-rent strategy, you buy a property as your primary residence, live there for a period of time (usually at least a year), and eventually turn it into a rental. In some cases, you may even be able to take advantage of opportunities like renting out a room or a basement while you live there.
This can be a great way to get started, especially since owner-occupied financing may allow you to buy with a smaller down payment than a traditional investment property loan.
In this article, we’ll look at how the live-in-then-rent strategy works, why the financing can be attractive to real estate investors, how renting out part of the home may reduce your housing cost, and how the property may eventually become a long-term rental.
What is the Live-In-Then-Rent Strategy?
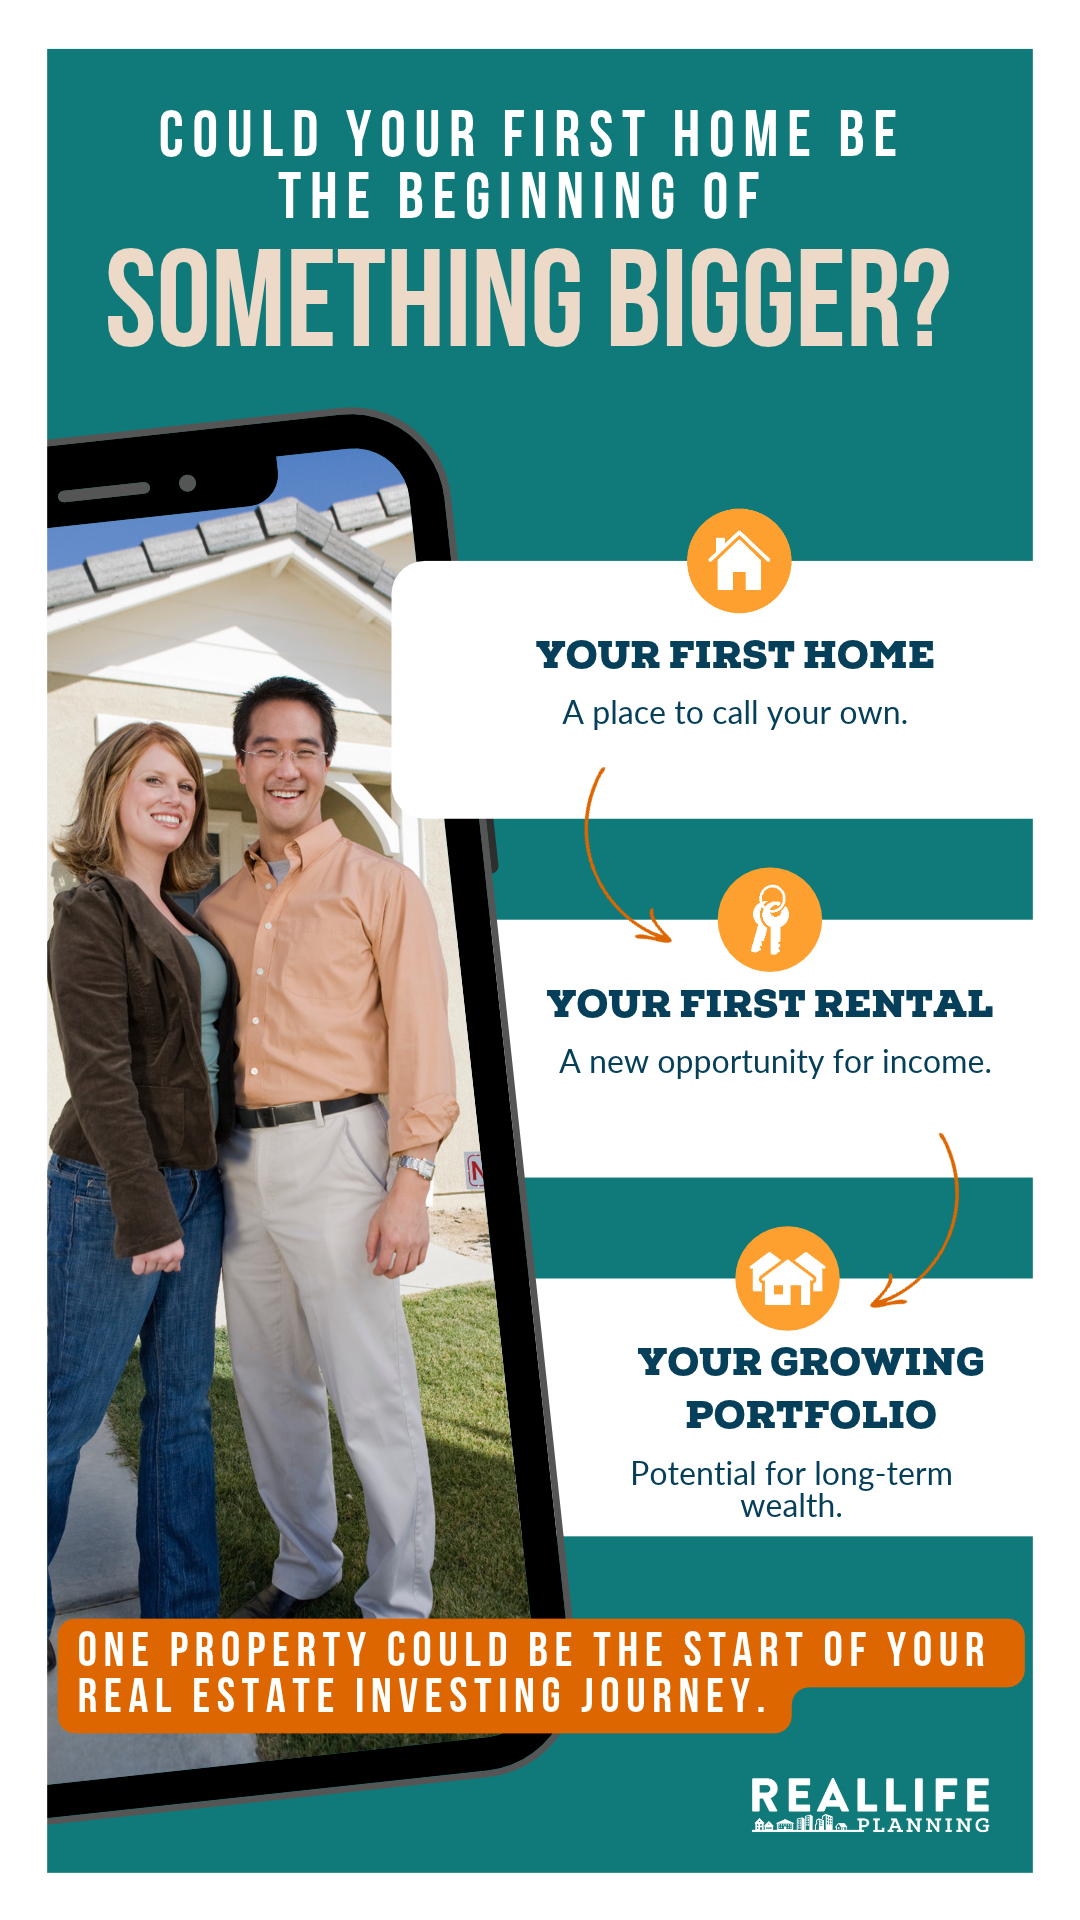
The live-in-then-rent strategy is exactly what it sounds like: you buy a home, live in it, and later turn it into a rental property.
Instead of buying a separate investment property right away, this strategy allows you to purchase the property as your primary residence. That means you plan to live there and follow the occupancy requirements for the loan you use.
Many owner-occupied loan programs require you to intend to continuously live in the home for at least 12 months; however, the specific rules can vary by loan type and lender, so it’s important to understand those requirements before you buy a property.
While you’re still living in the property, you may also be able to rent out a part of the home, depending on the layout and local restrictions. That could mean renting out a room, a basement, an accessory dwelling unit (ADU), or another part of the property that makes sense.
After you’ve satisfied the occupancy requirements and are ready to move, the property can become a full rental. For a first-time buyer who wants to start investing in real estate, this can be a bridge. You’re buying a home to live in today, but you’re also thinking about the home as a part of your rental property portfolio for later.
Why Owner-Occupied Financing Can Make a Live-In-Then-Rent Strategy More Accessible
 One of the reasons the live-in-then-rent strategy can be easier for beginner real estate investors is because of the financing.
If you buy a traditional investment property that you don’t plan to live in, you may be expected to make a larger down payment, typically ~20-25%. For many new investors, that can make the first property feel out of reach.
Owner-occupied financing, on the other hand, can be much less expensive up front. Because you’re buying the property as your primary residence, you may be able to use loan options that require less money down.
Depending on the loan type and your qualifications, options such as conventional, FHA, VA, or other owner-occupied loans may allow some buyers to purchase with a much smaller down payment than a traditional investment property loan, usually closer to 3-5%. If you are eligible, a VA loan may not require any down payment. This can make it much easier to get into a property sooner, especially if you’re buying a home you can live in now and potentially rent out later.
However, a lower down payment doesn’t mean the property is automatically a good fit. You still have to consider the monthly mortgage payment, mortgage insurance, closing costs, repairs, cash reserves, and the ongoing cost of owning and maintaining the home.
The financing may help you get into the property; renting out part of the home may help with the monthly cost of owning it.
 How Renting Out Part of the Property Can Change the Numbers
Let’s say you buy a three bedroom two bathroom home with a two car garage for $400,000 and put 5% down, or $20,000. That leaves you with a mortgage of about $380,000. For this example, we’ll assume the total monthly housing cost is around $3,300, including principal, interest, property taxes, and mortgage insurance.
If you live in the property and do not rent out any part of it, you’re paying the full $3,300/month yourself. Over the course of a year, that’s $39,600 out of pocket.
Now let’s say you rent out one part of the property. Maybe that’s a spare bedroom, a basement with a separate entrance, an accessory dwelling unit, or another space that makes sense. If that space rents for $1,000 per month, your out-of-pocket housing cost drops from $3,300 to $2,300 per month — which is a difference of $12,000 per year.
If you rent out two spaces and bring in a combined $2,000 per month, your out-of-pocket cost drops to $1,300 per month, or $15,600 per year.
At the same time, you’ll still be building equity in the property. Part of each mortgage payment goes toward paying down the loan. In this example, let’s say approx. $7,000 goes toward principal paydown in the first year.
The property may also appreciate. If the $400,000 property appreciated by 3%, that would be another $12,000 in potential value growth.
Together, that could represent about $19,000 in wealth building in the first year:
- $7,000 from principal paydown
- $12,000 from appreciation
Appreciation is not guaranteed, and actual principal paydown depends on the loan terms. You also still need to account for repairs, reserves, vacancies, utilities, insurance, and local rental rules.
But this example shows why house hacking, using a property that you live in to generate income, can be a great way for beginner real estate investors to get started. The rental income may help reduce your cost of living while you’re also building equity in a property you own.
What Happens When You Move Out?
 After you meet the occupancy requirements for your loan, you may be able to move out and turn the property into a full rental. This is where the live-in-then-rent strategy can be part of a long-term real estate investing plan; the home you bought as your primary residence may become the first rental property in your portfolio.
Using the same example, let’s say your monthly payment is still around $3,300. After you move out, you rent the full property for $3,400 per month.
At first, that may only leave about $100 per month in cash flow before considering other expenses and reserves. That may not sound like much, but the property could still be helping you build wealth in other ways.
Over time, rents may increase while the mortgage payment stays more stable, aside from changes to taxes and insurance. Your property may also continue to benefit from principal paydown, appreciation potential, tax benefits, and long-term asset growth.
For some buyers, this strategy can create a path from first-time homeowner to real estate investor. Instead of waiting until you have enough saved for a separate investment property, your first home may become the foundation for your rental portfolio.
What to Consider Before Using the Live-In-Then-Rent Strategy
The live-in-then-rent strategy can be a useful way to start building a real estate portfolio, but it still needs to fit your actual life and your actual numbers.
Before you buy, we urge you to ask yourself:
- Can you afford the property if the room, unit, basement, or ADU is vacant?
- Do you have enough cash reserves for repairs, maintenance, and any unexpected expenses?
- Are you comfortable sharing space with a renter or living close to tenants?
- Does the layout of the property work for renting out part of the home?
- Are there local rental rules, HOA rules, zoning restrictions, or insurance requirements to understand?
- What are the occupancy requirements for your loan?
- After you move out, does the property still work as a rental?
- How does this fit into your larger financial plan?
These questions can be helpful to think about because a property may look like a good house hack while you live there, but you also want to understand what happens later. You’ll want to know that the rent will reasonably cover the mortgage and expenses, and that you have the reserves to handle unexpected expenses.
A Practical Way to Start Investing in Real Estate
The live-in-then-rent strategy can be a practical way for some buyers to start building wealth through real estate sooner than they expected.
By purchasing a property as a primary residence, you may be able to use owner-occupied financing and reduce the amount of money needed upfront. Renting out part of the home while you live there may also help lower your monthly housing cost.
At the same time, you may be building equity through principal paydown and potential appreciation. Then, after you meet the occupancy requirements and are ready to move, that first home may become the first rental property in your portfolio.
Of course, you’ll want to run the numbers yourself. This strategy requires cash reserves, realistic rental income assumptions, a plan for repairs and vacancies, and a clear understanding of the loan rules. The property should make sense as a place to live now and as a potential rental later.
If you’re a real estate investor looking for more tips and insights around rental property ownership, we’d love for you to check out more from the Real Life Blog.